01

01
Financial Toolset
financialtoolset.com
Calculate if buying mortgage points is worth it. Compare discount points vs higher rate. Free mortgage points calcula...
Homebuyers and homeowners navigating the complexities of mortgage financing use the mortgage points calculator to evaluate the long-term financial impact of paying discount points. By entering loan details such as the principal amount, interest rate, and the cost of points, users determine how much their monthly payment decreases and how long it takes to reach the break-even point on the upfront...
Calculate if buying mortgage points is worth it. Compare discount points vs higher rate. Free mortgage points calcula...

The mortgage points calculator helps you estimate and compare the savings gained when buying mortgage points.
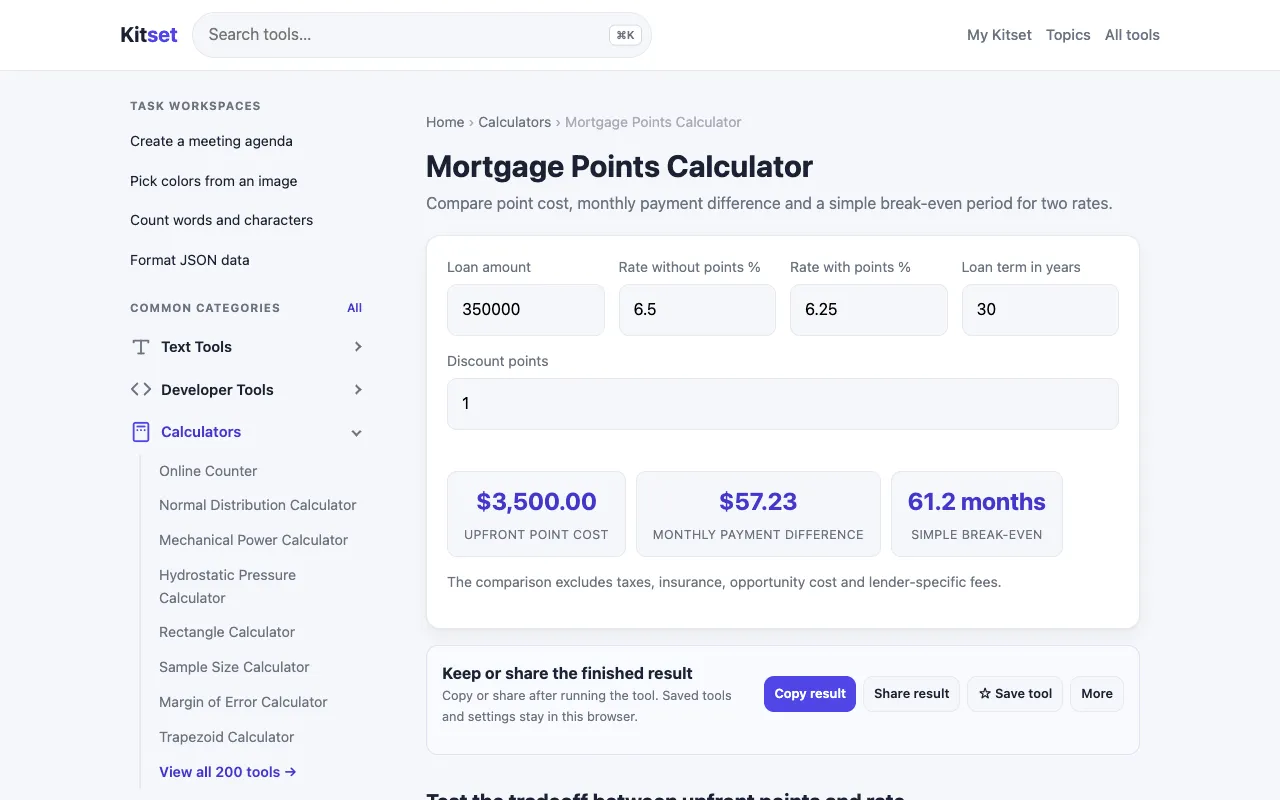
Estimate mortgage discount point cost, monthly payment savings and simple break-even months for two fixed interest ra...
Side by side
| Tool | Best for | Strengths | Limitations |
|---|---|---|---|
| Financial Toolset financialtoolset.com | Quick break-even analysis |
|
|
| Omni Calculator omnicalculator.com | Side-by-side scenario comparison |
|
|
| Kitset kitset.app | Simple two-rate point cost comparison |
|
|
Buyer's guide
When picking a mortgage points calculator, the key numbers you need are loan amount, current interest rate, the cost of discount points, and the new lowered rate. Those four inputs let the math show your monthly savings and how many months of savings it takes to recoup the upfront point cost. If you only need one scenario, a tool that displays monthly payment and total interest clearly is enough. If you are weighing two different point options — for example, paying 1 point to drop the rate by 0.25% versus paying 0.5 points for a 0.5% drop — you will want a calculator that lets you input both sets of rates and see the break-even side by side.
Questions