Business Tools2 options compared

Dscr Calculator

Real estate investors and commercial lenders rely on the Dscr Calculator to evaluate the financial health of income-producing properties. By comparing a property's net operating income to its total debt obligations, the calculator determines the Debt Service Coverage Ratio, a critical metric for assessing loan eligibility and investment risk. It simplifies the process of determining whether a...

Editors’ Top PickBased on community votes
Other OptionsRanked by votes
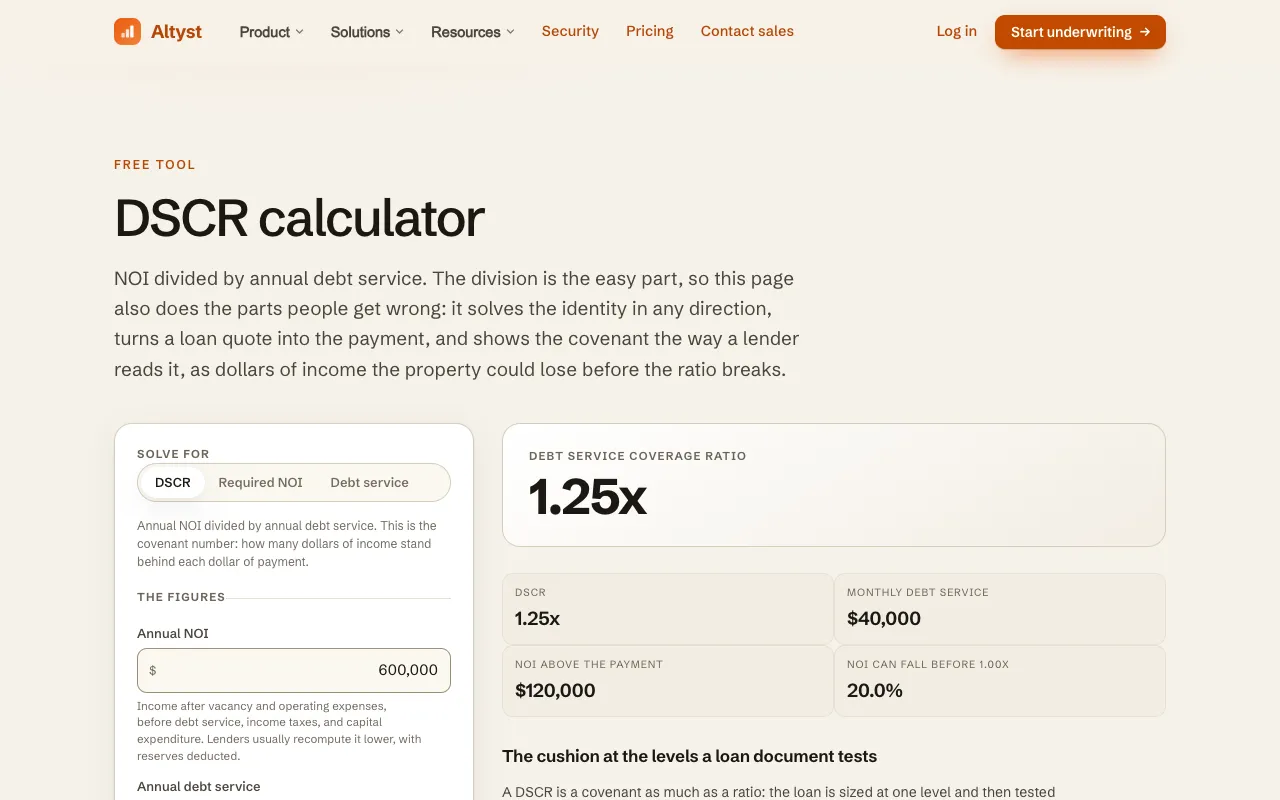
  1. Screenshot of Altyst
    02
    Altyst
    altyst.ai

    Free DSCR calculator. Enter any two of NOI, annual debt service, and DSCR and it solves the third, computes the payme...

Side by side

Dscr Calculator options compared

ToolBest forStrengthsLimitations
Financial Toolset
financialtoolset.com
Investors needing full cash flow analysis
  • Includes vacancy and operating expense inputs
  • Outputs NOI, debt service, and annual cash flow
  • Shows operating expense ratio alongside DSCR
  • Ads on the page
  • Fewer unit options compared to specialized calculators
Altyst
altyst.ai
Quick DSCR solves without signup
  • No signup or email required
  • Solves for any variable (NOI, debt service, DSCR)
  • Shows covenant level income drop before ratio breaks
  • Fewer input fields for property expenses
  • No integrated amortization or cash flow forecasting

Buyer's guide

How to choose a dscr calculator

When picking a DSCR calculator, first decide whether you need a full property cash flow model or just the ratio itself. If you are underwriting a deal, you will want vacancy rates, operating expenses, and loan terms all on one screen so you can see the net operating income and annual cash flow together. If you already have a loan quote and just need to check the math or test how much income could drop before hitting a lender covenant, a minimal tool that lets you solve for any variable is faster and less distracting.

Questions

Dscr Calculator FAQ

What is a good DSCR ratio for a rental property?
Most lenders want to see a DSCR of at least 1.25, meaning the property generates 25% more income than the annual debt service. A ratio below 1.0 means the property does not produce enough cash flow to cover the loan payment.
Can I use DSCR to compare different loan terms?
Yes. By keeping the net operating income the same and changing the loan amount, interest rate, or term, you can see how the DSCR shifts. This helps you understand how much you can borrow while still meeting a lender's minimum coverage requirement.
Does DSCR include taxes and insurance?
No. DSCR uses net operating income, which is income after operating expenses but before debt service, taxes, and capital expenditures. Property taxes and insurance are typically included in operating expenses, but income taxes and loan principal are excluded.
What happens if my DSCR is exactly 1.0?
A DSCR of 1.0 means the property's net operating income is exactly enough to cover the annual debt service. There is no cushion for vacancies, unexpected repairs, or tax payments, which most lenders will not accept.
How do I calculate DSCR if I only know the monthly payment?
Multiply the monthly payment by 12 to get the annual debt service, then divide the net operating income by that amount. Some calculators, like the one on Altyst, let you input a loan quote and will derive the payment automatically.
Keep Exploring

Related tools in Business Tools

View all →